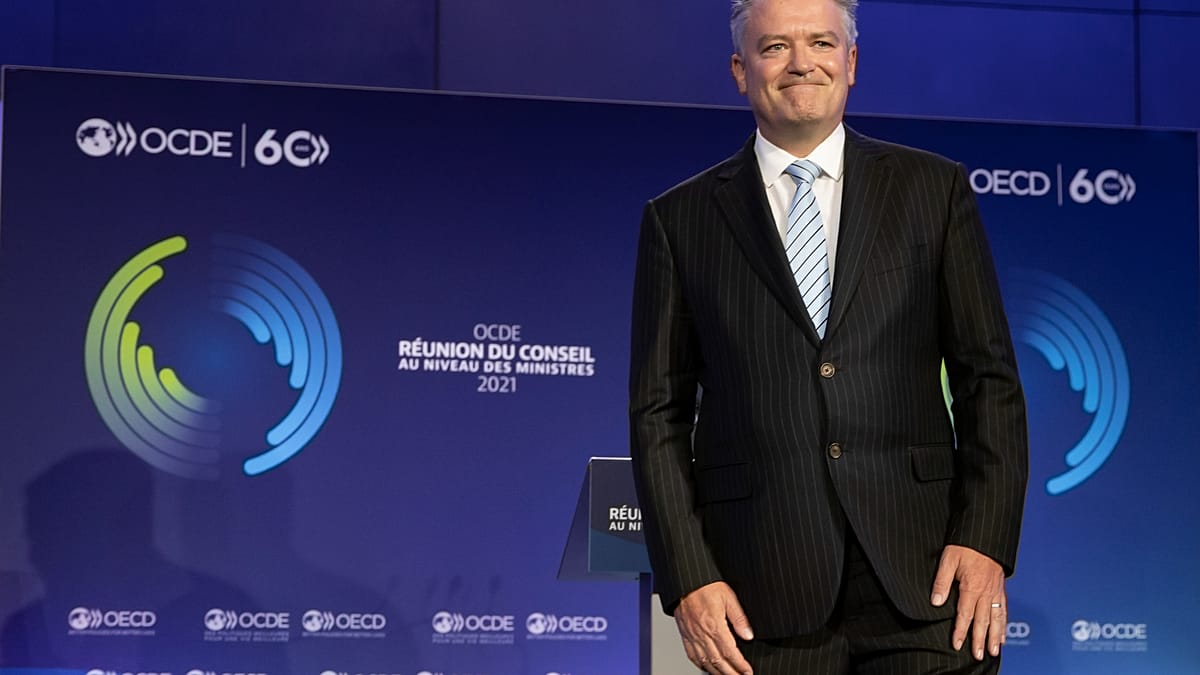
Europe stands at a crossroads. The artificial intelligence revolution offers the continent its biggest productivity leap since the advent of computers and the internet. But as OECD Secretary-General Mathias Cormann warned this week, Europe missed much of that earlier wave. It cannot afford to repeat the mistake.
Speaking after two days of meetings with EU finance ministers in Dublin—the Eurogroup on productivity and the informal ECOFIN on AI—Cormann framed the challenge in stark terms. AI is not merely a technology issue; it is a growth, income, and budgetary question, and increasingly one of competitiveness and security.
The productivity gap
Europe's productivity growth has been sluggish for decades. Since 2022, output per hour across the EU has essentially stagnated, while the gap with the United States has widened. That stagnation has real consequences: wages stall, living standards plateau, and the cost of living becomes harder to bear.
Demographics compound the problem. The EU's working-age population is shrinking. Today, there are about three people of working age for every person over 65; by 2060, that ratio will fall below two. Pensions, healthcare, and long-term care will demand more public spending each year, while defence and the energy transition add further pressure. OECD analysis suggests these pressures could add nearly six percentage points of GDP to public expenditure in many European countries by 2040.
Higher taxes or more debt are not viable answers. Tax burdens in much of Europe are already among the highest globally, and debt servicing costs are climbing. The only sustainable path is faster growth—but with fewer workers, that growth must come from productivity. AI offers precisely that opportunity.
The AI dividend
According to OECD estimates, AI could add up to 1.2 percentage points to annual productivity growth over the next decade. That would generate revenue without raising tax rates—a fiscal dividend that could help fund care for an ageing population, invest in security, and bring down debt. AI could also make public services themselves more efficient.
But none of this is automatic. The dividend only materialises if AI is adopted across the entire economy. While usage is rising—one in five OECD firms used AI last year, double the share two years earlier—adoption remains narrow. Half of large firms use AI, but only one in six small ones do, with dramatic variation across sectors.
Cormann outlined three priorities for Europe. First, build the infrastructure: data centres, reliable and affordable power, and fast networks. Permitting must be faster, and Europe's electricity market better integrated so power flows where needed. The AI build-out is a trillion-euro investment wave, increasingly financed through bond and capital markets rather than company cash flows. Europe has ample savings, but too much sits in bank deposits or flows abroad. A genuine capital markets union would channel those savings into European infrastructure and provide young, innovative firms with the risk capital they need to scale.
Second, ensure access. Small and medium-sized enterprises employ most Europeans. They need affordable tools, trusted advice, and a single market where a product built in one member state sells across all 27.
Third, invest in people. Skills are the binding constraint on faster adoption. Firms consistently say they cannot find workers who can use AI. Yet workers are ahead of their employers: more than 40% of employed people across the OECD already use generative AI tools, often on their own initiative. What is missing is training—and it reaches those who need it least. Only 23% of adults with low literacy participate in AI-related training, compared with 61% of those with high literacy.
Firms under-invest in training because they fear losing trained employees. That market failure can be corrected with fiscal tools: tax treatment of training, incentives for employers who train, and individual learning accounts that workers carry from job to job.
Jobs and risks
Fears of mass unemployment dominate headlines, but the data do not support them. OECD surveys find no evidence that AI is reducing overall employment. If anything, sectors most exposed to AI are advertising more jobs, not fewer. On young people, where concern is loudest, the OECD's Employment Outlook finds AI's role in their difficulties has so far been limited.
Change is inevitable—some tasks will disappear, new ones will emerge. The right response is systematic preparation: training for workers most at risk, employment services that move people from job to job rather than through unemployment, and help for those who must relocate. AI itself can make training more effective—shorter, more targeted, easier to deliver. Holding back the technology is not the answer.
Europe must manage AI's risks to privacy, safety, cyber security, and financial stability. The OECD AI Principles provide a shared framework. But as Cormann stressed, the greater risk for Europe is not moving too fast—it is moving too slowly while others race ahead. In a world where economic strength and security are ever more closely linked, hesitation is the luxury Europe cannot afford.