For years, investors treated French government bonds as nearly as safe as German ones. That assumption is now crumbling at remarkable speed. Last week, the yield on France's 10-year bonds climbed to around 5%, a level not seen since July 2002. The premium investors demand to hold French debt over German Bunds widened to 152 basis points, the most since the eurozone debt crisis of 2011-2012.
Strikingly, France now pays more to borrow than Italy or Greece, the two countries that were at the epicentre of that earlier crisis. This shift matters far beyond the bond market: government borrowing costs influence mortgage rates, business loans, and the interest bill that every French taxpayer ultimately bears.
How did France get here?
The root cause is simple: the French state spends more than it collects in taxes, year after year, and borrows to cover the gap. In 2026, the deficit is projected to reach 5.4% of GDP, well above the EU's 3% limit. These deficits have piled up into a mountain of debt, which reached €3.6 trillion in the second quarter of 2026, equivalent to 119% of GDP, according to INSEE, the national statistics office.
The trouble begins when investors start to doubt the government's ability or willingness to repay. France has a plan, but its track record is shaky. Prime Minister Sébastien Lecornu's minority government presented its 2027 draft budget on Thursday, proposing around €54 billion in spending cuts and revenue increases. The goal is to bring the deficit down to 5% of GDP next year, with two-thirds of the adjustment coming from spending restraint and one-third from higher taxes. Measures include €6 billion in savings each from pensions and healthcare, and a freeze on non-interest, non-defence spending in cash terms.
Yet the budget did not calm investors; it worried them. Lecornu lacks a parliamentary majority, the National Assembly begins debating the text on 13 October, and a presidential election is due in spring 2027. Stéphane Colliac, an economist at BNP Paribas, notes that France has missed its budget targets in three of the four years between 2023 and 2026. He calculates that rising interest payments and defence spending mean the government must find savings worth about 1% of GDP just to cut the deficit by 0.4 percentage points.
Supply is adding to the pressure. The French Treasury plans to issue €340 billion of debt in 2027, €20 billion more than this year, as pandemic-era borrowing matures. Even if everything goes to plan, Colliac expects debt to rise to 121% of GDP in 2027 and only stabilise at 124% by 2032.
Why is the risk blowing up now?
The speed of the move is as alarming as the level. Intesa Sanpaolo strategists, led by Gian Marco Salcioli, argue that when yields jump this fast, the market's focus shifts from the cost of borrowing to the risk of default. "The move tends to transform rate risk into something broader, first and foremost credit risk," Salcioli wrote. Enrique Díaz-Alvarez, chief economist at Ebury, called it "the largest weekly widening in said spread in seventeen years."
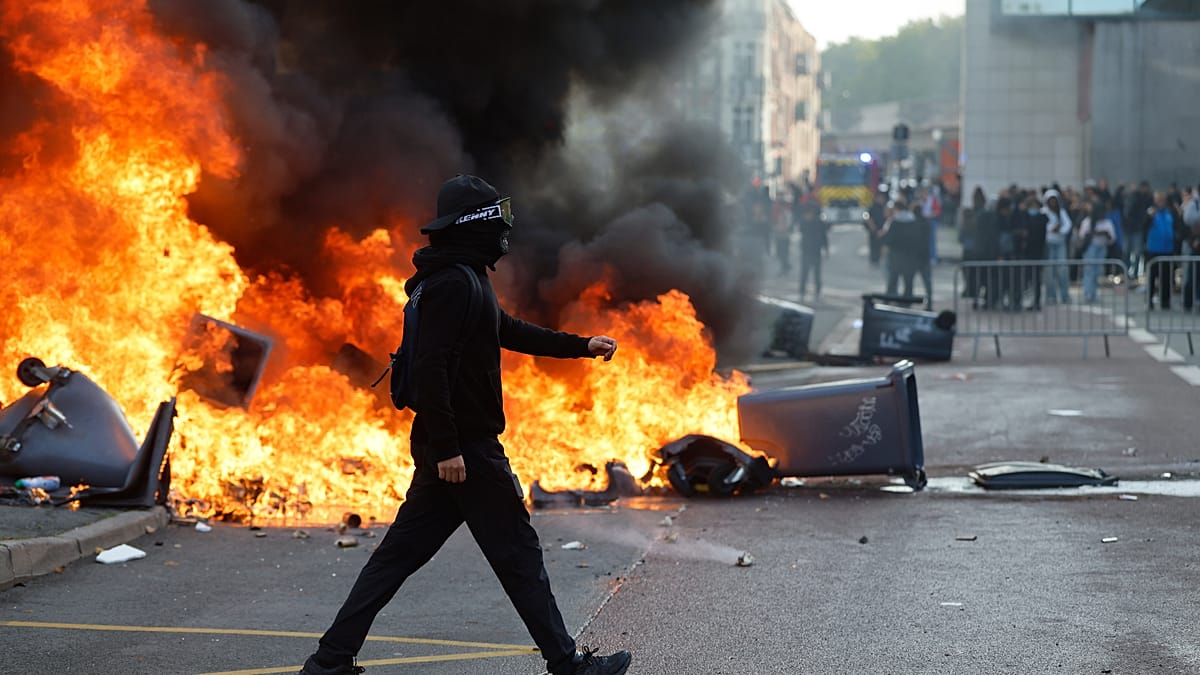
Political deadlock is at the heart of the problem. The government's proposals have met with scepticism from the fiscal watchdog, and student protests over underfunded schools have added to the pressure. The student revolt has seen clashes with police in Marseille and Lille, and schools have been torched in Paris, reflecting broader social discontent.
Could the crisis spread across Europe?
There are already warning signs. ING strategists Michiel Tukker and Benjamin Schroeder report that Italian and Greek spreads over German Bunds have widened by almost 15 basis points during the French turmoil. "Debt dynamics are no longer deemed only a French problem," they wrote.
Currency markets are also reacting. Intesa's currency analysts note that the euro touched $1.1161 in Asian trading on Monday, despite weaker US employment figures, and warn that French fiscal concerns could push it towards $1.10. For the European Central Bank, this creates a difficult balancing act. Eurozone inflation rose to 3.8% in September, strengthening the case for continued tightening, while stress in government bond markets bolsters the case for a pause.
The ECB has a targeted tool, the Transmission Protection Instrument, to counter unwarranted market disruption. But support depends on factors including debt sustainability and fiscal-policy compliance. It is not an unconditional guarantee of French borrowing costs. Such purchases can address disruptive differences in borrowing costs between countries without requiring the ECB to cut its main interest rates.
How dangerous is it?
The immediate risk is that political deadlock prevents France from passing a budget. BBVA's Ana Munera warns that Lecornu could fail to secure sufficient parliamentary support and be forced from office. Without an approved budget, France would face a shutdown or emergency measures, further eroding confidence.
The broader danger is contagion. If investors begin to question the safety of other highly indebted eurozone members, the region could face a new debt crisis. The euro has already slid to a 17-month low amid these worries, and a Spanish snap election has added to the market jitters. The situation is fluid, and the stakes are high for the entire continent.