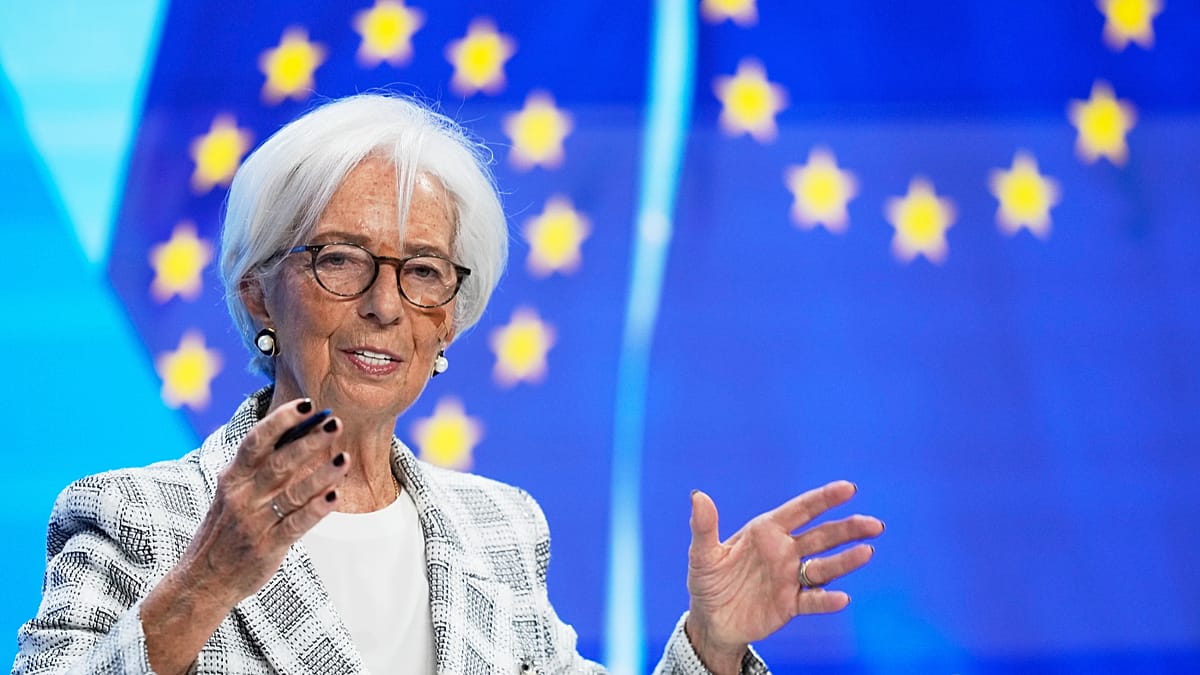
Christine Lagarde is stepping down from the European Central Bank (ECB) earlier than planned, and she has finally explained why: she can no longer stay silent. The ECB president, who will leave her post on 7 February 2027—about nine months before her term was due to end—told reporters in Frankfurt on Thursday that the neutrality demanded of central bankers, which she called "the price of their independence," had become untenable.
"I don't think that I can remain neutral," she said. "I'm interested in the truth, and I see the truth being very often damaged, contradicted by misrepresentation."
Her announcement came alongside another surprise: the ECB's Governing Council had seriously debated raising interest rates, even though it ultimately decided to hold them steady, with the deposit rate at 2.5%. The decision to hold was unanimous, Lagarde said, but she made clear that the pause might only last until December.
Why a hike was on the table
Lagarde pointed to two developments since the ECB's September forecasts. First, energy prices have continued to climb—petrol, diesel, and gas are all more expensive, and refining margins remain high. Eurozone inflation rose to 3.8% in September, with energy prices up 18.9% year-on-year.
Second, long-term borrowing costs have risen sharply. The average 10-year government bond yield in the eurozone has climbed by around 35 basis points since the cut-off date for the September projections. That matters because higher long-term yields do part of the central bank's work for it: when governments and companies pay more to borrow over ten years, mortgages and business loans become pricier, and spending slows. Mortgage rates in the eurozone rose to 3.8% in August from 3.5% in July, and banks have tightened lending standards for companies.
"If you combine these two factors, actually, the Governing Council debated whether a hike was appropriate," Lagarde said. In the end, the council judged it was "well positioned enough at this stage to hold" and that a "measured approach" remained appropriate.
December move on the cards?
Lagarde repeated the ECB's standard line that decisions are made "meeting by meeting" with no pre-commitment. But she went further than usual, listing the data the bank will receive before its December meeting—two more inflation readings, third-quarter growth figures, and wage data—and said those numbers would be checked against today's assessment. "Unless there were major developments, the direction of travel is quite clear for all of us," she said. She added that underlying inflation, which strips out volatile items like energy and food, would carry particular weight.
France in the spotlight
France was the elephant in the room. The country's 10-year borrowing costs rose above 5% last week for the first time since 2002, and the gap over German Bund yields has widened sharply. On Thursday, the French 10-year yield eased to about 4.88%, still roughly 154 basis points above Germany's and about 40 basis points above Italy's—a country long seen as the eurozone's weakest link on public debt.
Lagarde avoided naming France directly. She attributed the rise in long-term yields to global factors: inflation expectations, the expected path of interest rates, and a wave of bond issuance by large technology companies borrowing to build data centres. But she was clear that high-debt countries face a particular challenge. They must plan for interest rates that "will probably remain higher for a period of time," she said, and keep their budgets within Europe's fiscal rules.
Asked whether the ECB was watching for contagion risk, Lagarde struck a firmer tone: "Should market developments threaten the smooth transmission of our monetary policy, including through unwarranted and disorderly market movements, we have instruments available to respond." In other words, the ECB is prepared to intervene if turmoil in government bond markets becomes severe enough to block its interest rate decisions from reaching households and businesses as intended.
The ECB has intervened before, buying bonds of struggling eurozone countries during the debt crisis that began in 2010 and again during the pandemic. Its 2022 Transmission Protection Instrument has never been used. Oxford Economics does not expect it to be activated soon; its baseline sees the French-German spread approaching 200 basis points by next spring's presidential election. Leo Barincou, a senior economist at the research firm, said in a note that there is "likely some room" between that scenario "and an actual debt crisis."
What's next for Lagarde and the ECB?
Lagarde said her mandate would have ended in October 2027 in any case. Leaving in February, she explained, gives her back the freedom to speak and act on issues beyond monetary policy. After more than 20 years at the IMF and the ECB, she added, there were things she felt she should say. "Whether people will listen or not is another story."
She declined to say whether she would back a candidate in France's presidential election next spring, or what job she will take next. On the succession, she insisted there would be "perfect continuity of business." "The institution is solid, strong like a rock," she said.
Not everyone is so relaxed about the timing. "The timing for the ECB is far from ideal," Matthew Ryan, head of market strategy at financial services firm Ebury, said in an emailed comment, pointing to inflation well above target and a French-German spread at its widest since 2011. Ryan sees former Dutch central bank chief Klaas Knot and Bank of Finland governor Olli Rehn as potential successors. The ECB's leadership transition comes at a delicate moment, as the institution navigates rate policy with inflation near double target and growing market pressures.